The implementation of a RM300,000 cap on vehicle tax exemptions in Labuan and Langkawi from January 2026 marks an important change to the tax privileges enjoyed by the two duty-free territories.
From an economic perspective, the measure can be viewed as a form of targeted restructuring of incentives. The government has not completely removed the tax advantages enjoyed by consumers, but has limited the benefits so that they are not overly concentrated on the purchase of high-value vehicles.
In other words, those purchasing vehicles worth RM100,000 or RM200,000 will still enjoy the exemption provided. However, for vehicles priced above RM300,000, buyers will no longer enjoy the same level of benefit as before.
This approach reflects a fundamental question in fiscal policy: Who should actually benefit from a tax exemption?
If the original objective of the exemption is to assist local residents, stimulate economic activity and maintain the attractiveness of duty-free territories, there is a rationale for distinguishing between ordinary vehicle purchases and luxury vehicle purchases.
Closing Leakage, but Implementation Must Be Effective
The RM300,000 cap also has the potential to reduce leakage in the provision of tax exemptions, particularly where substantial benefits were previously enjoyed through the purchase of luxury vehicles.
However, setting a threshold alone does not necessarily guarantee the effectiveness of the policy.
The more important questions are how vehicle prices will be assessed, how the regulations will be enforced and how the authorities will ensure that there is no manipulation of values, registration or other methods to circumvent the tax.
Without transparent and consistent valuation mechanisms, the objective of making the exemption more targeted may not be fully achieved.
At the same time, the RM300,000 figure should not necessarily be regarded as a permanent threshold.
Vehicle prices can change due to inflation, foreign exchange movements, new technologies and changes in market structure. A vehicle considered premium today may fall into a more mainstream segment several years from now.
Therefore, the threshold should be reviewed periodically to ensure that it remains relevant to prevailing economic conditions.
Labuan’s Car Market May Shift
For the automotive industry in Labuan, the impact is not necessarily negative across the board. Instead, the effects may vary according to market segments.
Dealers that mainly sell vehicles priced below RM300,000 may not experience significant pressure. In fact, consumers may shift their demand towards vehicles within this price range to continue benefiting from the tax exemption.
This could make the mid-range vehicle segment more attractive.
Greater challenges may be faced by dealers that rely heavily on sales of luxury vehicles priced above RM300,000. As the tax increases the effective price paid by consumers, some buyers may postpone their purchases, opt for cheaper models or seek other alternatives.
The used luxury vehicle market should also be monitored.
If the appeal of owning luxury vehicles in Labuan declines as a result of changes to the tax structure, transaction volumes could slow and the time required to sell individual vehicles could become longer.
In such circumstances, dealers may need to adjust their business strategies by shifting from an excessive focus on the luxury segment towards stocking more mid-range vehicles, which could have a broader demand base.
This illustrates how changes in tax policy can affect not only prices, but also demand patterns and the structure of the local market.
Labuan Is More Than Just a Car Market
However, the issue should not be viewed solely from the perspective of the automotive industry.
Labuan’s duty-free status is part of the island’s economic identity and attractiveness. Therefore, any changes to exemptions should take into account their impact on public and investor perceptions of the advantages of conducting economic activities, living and spending on the island.
Maintaining the exemption up to RM300,000 means Labuan still retains certain advantages compared with completely abolishing the exemption.
However, a balance needs to be achieved.
If the restrictions are too lenient, the government may continue to forgo revenue from the purchase of very high-value assets. If the restrictions are too stringent, Labuan’s competitive advantage as a duty-free territory could gradually diminish.
Government Gains Revenue, but Spillover Effects Should Not Be Ignored
From the government’s financial perspective, imposing taxes on high-value vehicles could generate additional revenue from consumers who can afford to purchase premium assets.
It could also reduce the fiscal cost arising from overly broad exemptions.
However, the benefits to the government should not be measured solely by the amount of tax collected.
The automotive industry has a longer economic chain. Vehicle sales support activities involving dealers, financing, insurance, workshops, maintenance and various related services.
If sales of luxury vehicles decline too sharply, some of these supporting economic activities could also be affected.
Therefore, policy analysis should consider the net impact on the economy, rather than merely the direct revenue generated for the government.
Ultimately, the success of the policy should not be assessed based on a single figure.
It is not simply a question of how much additional tax revenue can be collected.
The policy needs to achieve at least three objectives simultaneously: reducing leakage from tax exemptions, improving government revenue efficiency and, at the same time, ensuring that Labuan’s economic attractiveness is not excessively eroded.
This is the real challenge for policymakers.
A good tax exemption is not necessarily one that is the broadest, but one that reaches the right target without undermining the economic strengths it is intended to preserve.
In the context of Labuan, the message is clear: the duty-free advantage remains important, but that advantage must also evolve in line with economic changes.
The RM300,000 cap does not mean Labuan’s advantages have been abolished. Instead, it narrows the scope of the benefit to make it more targeted.
The key question moving forward is whether its implementation can genuinely achieve a balance between fiscal fairness, government revenue and Labuan’s economic competitiveness.
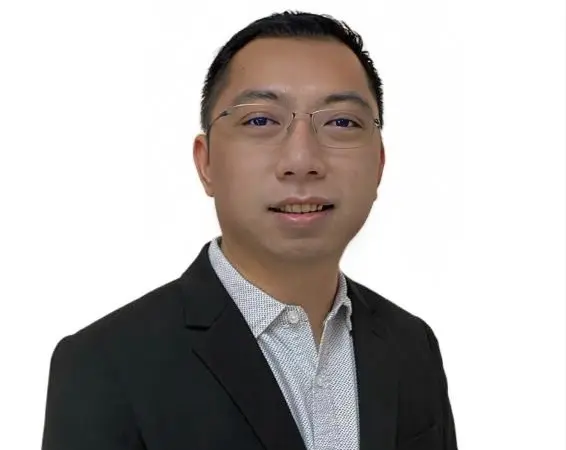
*The commentary was prepared by Dr Ricky Chia Chee Jiun, Deputy Dean (Academic and International) and Senior Lecturer at the Faculty of Labuan International Finance, Universiti Malaysia Sabah (UMS).